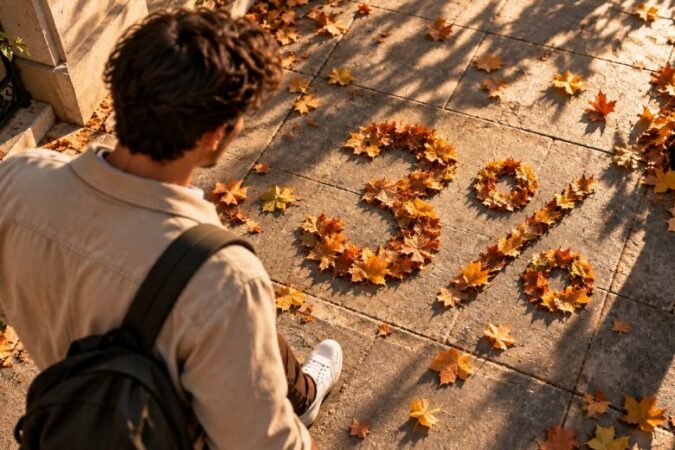

As 2027 approaches, along with holiday plans and December spending, it's also the time when many families take a simple stocktake: how much have we spent, how much have we saved, and what can we do differently next year?
The end of the year has a way of bringing us back to personal finances. After a year of small and large expenses, vacations, bills, and unplanned purchases, the question that remains is simple: what happened to the savings?
For many people, the answer is that some of it continues to stay at home or in a bank account, untouched, "just in case."
Having money available for emergencies is certainly important. But for savings that we know we won't need in the coming months, it might also make sense to think about alternatives that give them another function.
One of them is term deposits.
What happens to money when I put it in a deposit?
The concept is relatively simple: a sum of money is placed in the bank for a specified period and for this period it earns interest according to the terms established at the moment the deposit is opened.
For example, Intesa Sanpaolo Bank currently offers a 1-year deposit in Lek with a fixed annual interest rate of 3% , valid for new funds deposited with the bank until December 31, 2026.
The fact that the rate is fixed means that it does not change during the deposit period, even if the interest rates offered for new deposits change in the meantime.
To make it more concrete: an amount of 1 million lek , placed for one year at an interest rate of 3%, would generate about 30 thousand lek in gross interest , according to the full period of the funds remaining in the deposit.
Of course, before you decide, there are some practical conditions to consider. The offer applies to new funds and only in LEK currency. The deposit does not function as an account for daily payments and expenses, so a current account is required for these operations. Meanwhile, other amounts that may be added later are added to the existing deposit on the maturity date.
What about the safety of savings?
When it comes to savings, interest isn't necessarily the first question. For many families, knowing what happens to their money and how it's protected is more important.
In Albania, individual deposits in banks are insured by the Deposit Insurance Agency , in accordance with the legislation in force, up to the amount of 2.500.000 Lekë for each depositor in each bank.
This is also one of the reasons why term deposits continue to be an alternative used by those who want to be clear from the beginning about the savings period and the interest rate that will be applied.
The administration is also relatively simple. To open a deposit, a valid identification document, such as an ID card or passport, is required. A corresponding contract is issued for each opened deposit, while its status can also be followed through Digital Banking or at the bank branch.
Before 2027, it's probably worth taking a look at your personal finances.
There is no one way to save, nor is there a solution that fits every family. For one, the priority may be building an emergency fund; for another, it may be paying off a debt or saving for a down payment on a house, college, or travel.
But the end of the year can be a good time to make a simple division: what money might I need at any given moment and what can I put aside for a longer period?
Even a small decision made today can make the way we enter 2027 financially a little clearer.
For more information on the terms and conditions of the 1-year deposit in Lek of Intesa Sanpaolo Bank and to leave your contact details, you can visit:
Information can also be obtained at Intesa Sanpaolo Bank branches.